
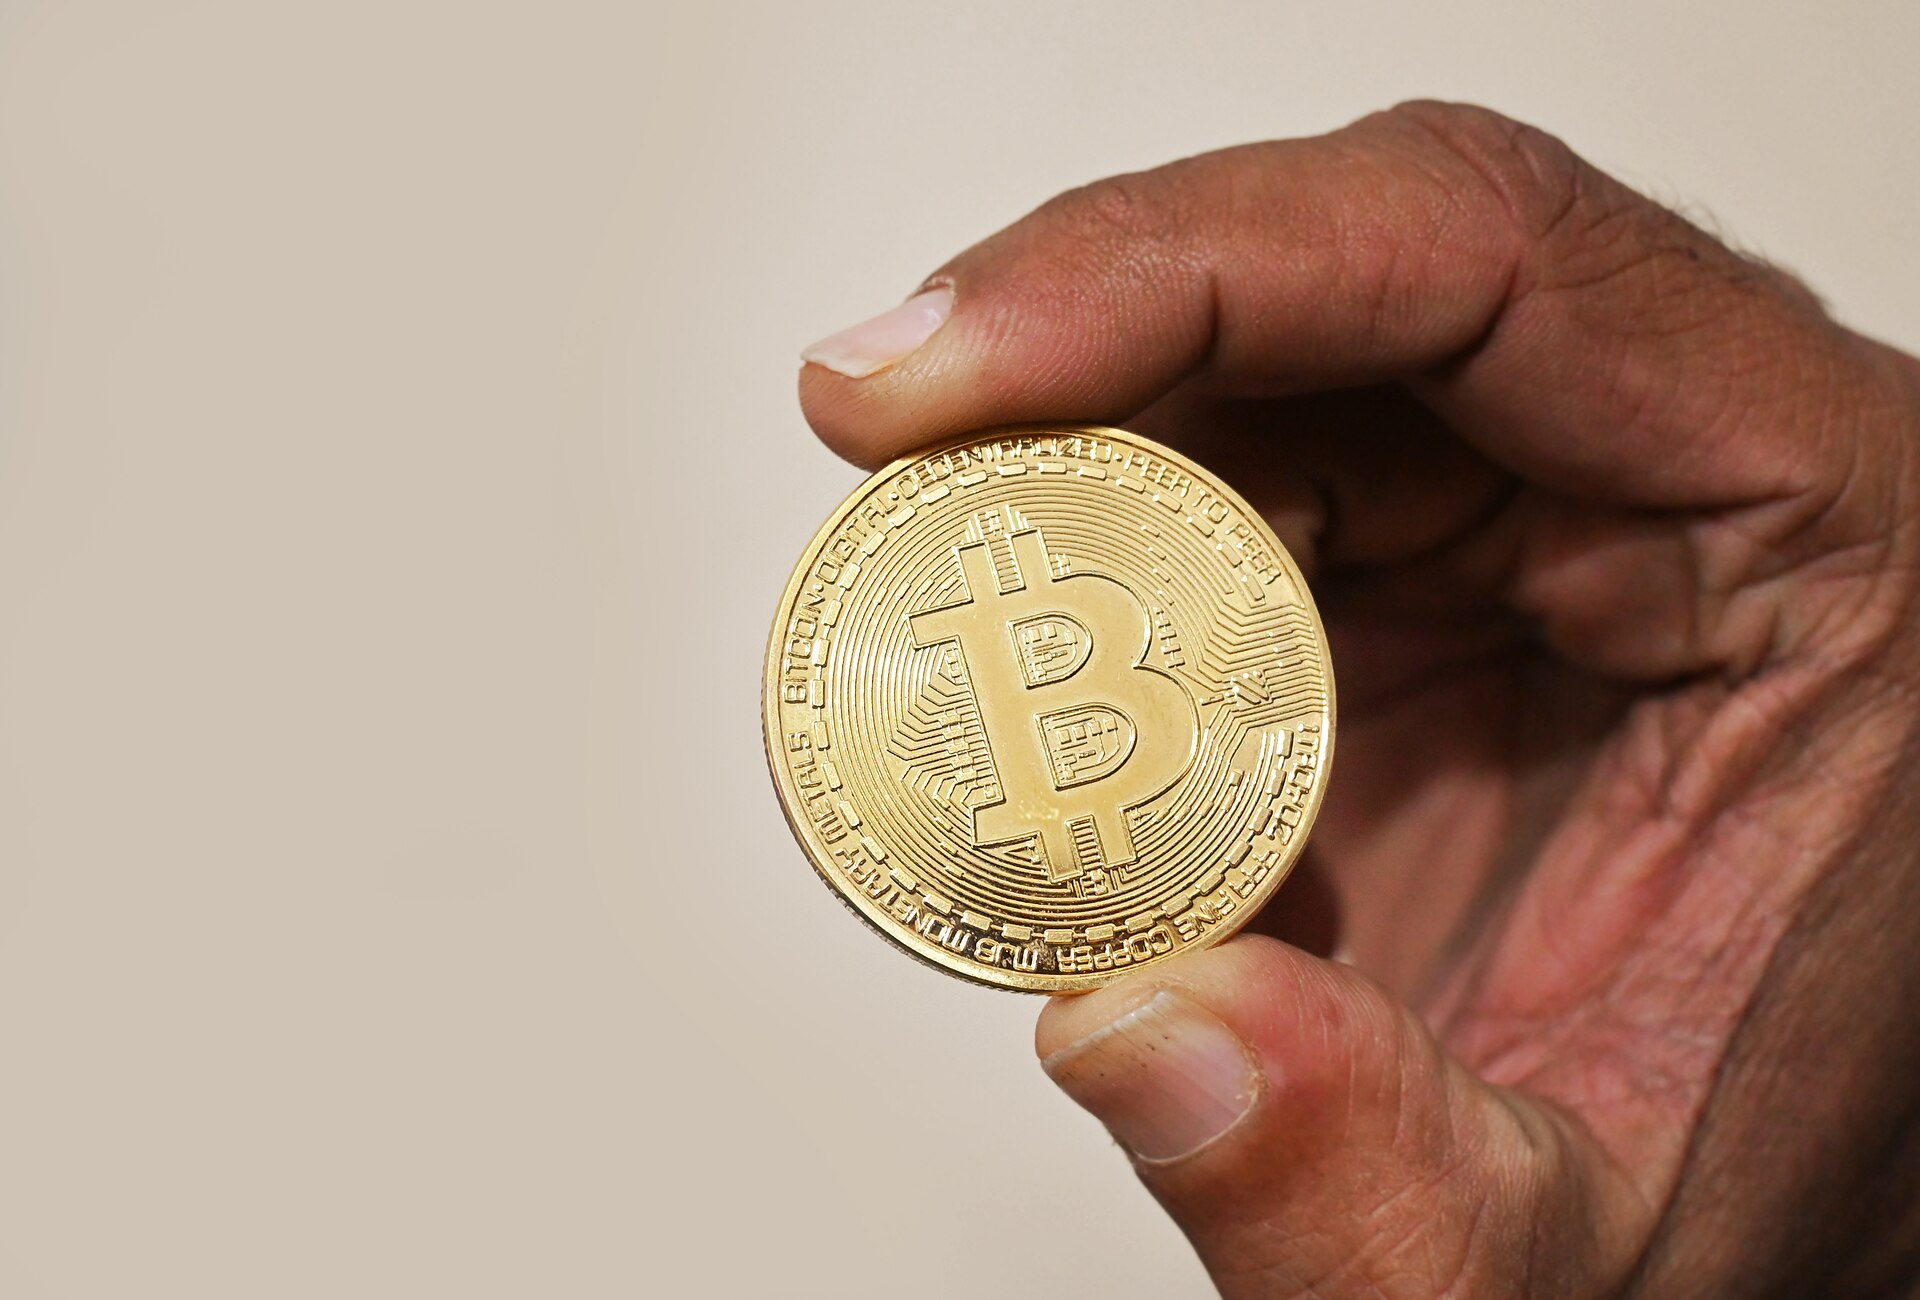
Cryptocurrency began as an experiment in money without institutions — no central bank, no regulator, no permission required. Well over a decade on, the experiment has grown into a market worth trillions at its peaks, and the institutions have arrived. Licensing regimes, tax reporting rules, stablecoin laws and courtroom battles are reshaping an industry that once prided itself on being impossible to regulate.
The change is not just legal. Large asset managers now offer crypto funds to ordinary savers, and banks that once refused crypto clients quietly provide custody services to the sector. At News Bush, we examine what this newer, more regulated era means for investors and for the technology itself.
Rules arrive, region by region
The European Union moved first with a comprehensive framework known as MiCA, which sets licensing and reserve rules for crypto firms and stablecoin issuers across the bloc. The rules are explained and overseen by the European Securities and Markets Authority, which supervises their rollout. Other jurisdictions have taken different paths — some courting the industry with clear licensing regimes, others restricting it heavily.
In the United States, the picture has been assembled piecemeal through legislation, agency guidance and litigation, leaving firms to navigate overlapping claims by market and banking regulators. The direction of travel, though, is consistent almost everywhere: exchanges must know their customers, segregate client assets and submit to independent audits.
Stablecoins have become the test case for this new approach. Because they promise a steady value backed by reserves, regulators increasingly treat them as a form of private money and demand the safeguards to match: high-quality liquid reserves, regular published attestations and a clear legal right for holders to redeem at par. Issuers that once operated from lightly regulated jurisdictions now queue for licences in major markets, calculating that legitimacy is worth more than freedom.
What regulation changes for ordinary holders
For people who simply hold or trade crypto, the practical changes are concrete:
- Licensed exchanges must safeguard client funds and publish proof of reserves
- Stablecoins are increasingly required to hold cash-like reserves, redeemable at par
- Tax authorities now receive reports of large trades, ending the era of assumed anonymity
- Marketing rules restrict the promises firms can make to retail investors
The overall effect is a market that looks more like mainstream finance: fewer spectacular collapses caused by opaque balance sheets, though regulation cannot remove price volatility, and a licence is not a guarantee against fraud or failure.
There are quieter effects too. Institutional-grade custody and insurance have made it easier for pension funds and corporate treasuries to hold digital assets, while clearer accounting and tax rules have removed long-standing excuses for staying on the sidelines. None of this guarantees that the market will grow — only that its growth, if it comes, will increasingly happen inside the financial system’s perimeter rather than outside it.
The debate that remains
Critics within the industry argue that heavy compliance costs entrench the largest firms and push innovation offshore, while privacy advocates worry about the financial surveillance that identity rules create. Consumer groups counter that the collapses of the early 2020s — which wiped out billions in customer funds — demonstrated exactly why minimum standards were needed. The Bank for International Settlements has repeatedly warned that crypto’s risks can migrate into the wider financial system as the links between the two grow.
The argument, in other words, is no longer about whether crypto should be regulated at all, but about how tightly, by whom, and at what cost to the openness that made the technology interesting in the first place.
What seems settled is the direction. Crypto is not disappearing, and neither is the rulebook. The industry’s next phase will be defined less by manifestos and more by compliance departments — a less romantic story, perhaps, but a more durable one. Follow the developments in our latest coverage.
